German Rare Earth Permit Signals EU Supply Chain Shift
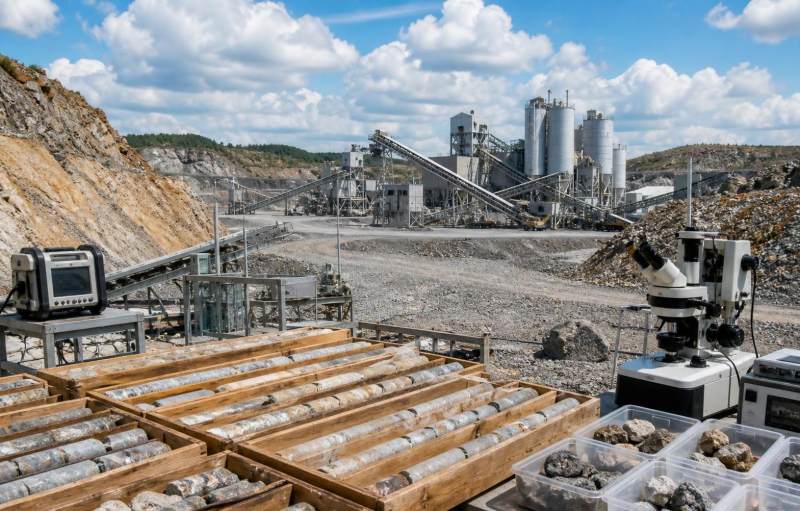
On July 31, 2026, the mining authority in Saxony approved Hades to carry out integrated rare earth and niobium exploration across 28.4 square kilometers in the Storkwitz area, creating a new regulatory and supply-chain signal for the European critical minerals market. For buyers, processors, exporters, and supply-chain service providers involved in rare earth magnets, separated compounds, and precursor materials, the development deserves attention because it points to a more concrete move toward domestic sourcing within the EU and may affect procurement timing, substitution reviews, and the reopening of long-term supply discussions.
A permit with direct supply-chain relevance
According to the provided information, the approval was granted on July 31, 2026 by the mining authority in Saxony for Hades to conduct combined rare earth and niobium exploration in the Storkwitz mining area. The approved exploration area covers 28.4 square kilometers. The project is described as Germany's first approved large-scale rare earth project. The stated estimated resource includes 38,000 tonnes of rare earth oxides and 8,000 tonnes of niobium pentoxide. The project fills a gap in Germany's domestic rare earth development and is presented as a sign that the EU is materially advancing a strategy to reduce external dependence in critical minerals.
Where the impact may begin to show
Procurement teams may revisit sourcing assumptions
Analysis shows that European procurement teams using rare earth permanent magnets, separated compounds, or precursor materials may treat this permit as an early signal to reassess supplier diversification. The immediate impact is less about near-term output and more about procurement planning, supplier screening, and the pace of replacement assessments. What deserves closer attention is whether purchasing departments begin requesting additional origin-related documentation, technical comparison materials, or revised supply proposals when discussing future contracts.
Chinese exporters may face a slower and more conditional buying cycle
From an industry perspective, exporters supplying European customers could see changes in the rhythm of inquiries and negotiations. The provided event summary already indicates likely effects on European customers' purchasing pace from China, as well as on substitution assessments and the renegotiation of long-term supply agreements. In practical terms, this may show up in contract review cycles, requests for more detailed technical documentation, and closer examination of delivery flexibility and traceability arrangements.
Processors and manufacturers may need stronger technical alignment
For processors and manufacturers in the rare earth value chain, the issue is not only supply availability but specification alignment. Observably, if buyers begin comparing current imports with future regional sourcing options, technical files, quality records, and product consistency documentation may receive more scrutiny during qualification or bid review. The key business effect would likely appear in pre-procurement evaluation, specification matching, and internal approval workflows rather than in immediate demand replacement.
Supply-chain and compliance service providers may see more document-driven work
Supply-chain service firms, testing-related providers, and compliance support teams may also be affected because a shift toward domestic critical-mineral sourcing usually increases attention on supporting records and qualification materials. Analysis shows that businesses serving procurement and trade functions should watch for changing customer requests tied to sourcing evidence, technical support files, delivery commitments, and audit-ready documentation, even though no specific new documentation rule was provided in the input.
What companies should watch now
Track the wording used in future official communications
It is more appropriate to understand this development as a concrete execution signal rather than a complete market outcome. Companies should therefore follow how public authorities and project stakeholders describe the next steps, because later wording may shape how buyers interpret sourcing reliability, qualification timing, and the seriousness of domestic substitution pathways.
Prepare for renewed contract and supplier reviews
Analysis shows that firms selling into Europe should be ready for customers to reopen long-term supply discussions. That does not automatically mean contract loss or immediate displacement, but it does increase the likelihood of requests for revised commercial terms, alternative delivery structures, and updated technical support materials tied to procurement resilience.
Strengthen product files for magnets, compounds, and precursors
Because the provided summary specifically points to rare earth permanent magnets, separated compounds, and precursor materials, companies in those product lines should review whether their technical documents, inspection records, and traceability materials are complete and current. What deserves closer attention is not a newly announced certification rule, but the possibility that procurement and qualification teams may apply stricter review standards as substitution options are studied.
Watch delivery planning and supplier qualification timing
Observably, the event may influence how European buyers sequence future orders and qualification work. Businesses should monitor whether customers begin spacing orders differently, adding more review stages before commitment, or linking delivery planning more closely to supplier-approval milestones. Since the input does not provide detailed implementation rules, these points should be treated as areas to monitor rather than confirmed outcomes.
Why this reads as an execution signal
From an industry perspective, this development is notable because it is tied to an approved exploration permit rather than a broad policy statement alone. Analysis shows that the market may read the approval as evidence that the EU's effort to localize critical-mineral supply chains is moving from strategy language into project-level execution. At the same time, it would be premature to treat the event as proof of near-term replacement of existing import channels. The more careful reading is that it introduces a stronger reference point for buyer behavior, procurement reviews, and future negotiations.
How the market may best interpret this stage
The industry significance of the Storkwitz permit lies in the regulatory signal it sends: domestic critical-mineral development in Europe is becoming more tangible at the project level. Analysis shows that the most immediate effects are likely to appear in sourcing reviews, substitution discussions, and long-term contract positioning rather than in instant physical supply changes. For now, it is more appropriate to understand this event as a grounded market signal with operational implications, while keeping final judgments open until further implementation details and market responses become clearer.
Basis of this article and what still needs verification
This article is based on the user-provided news title, event date, and event summary. For developments of this type, relevant source categories typically include official announcements, releases from regulatory authorities, information from trade or customs-related authorities, industry association updates, standards organization documents, and reporting by authoritative media. No specific official source link was provided in the input, so the underlying source trail still requires ongoing verification. What still needs to be watched includes later official statements, implementation language, changes in tender or procurement documents, certification or qualification expectations, market feedback, and how companies actually adjust execution in response.
Recommended News
- 2026.09.14Gel Battery Electrolytes: How Ionic Conductivity and Stability Shape Cell DesignElectrochemistry Fellow
- 2026.09.13Fluoropolymer Extrusion Process: How Melt Control Affects Tube QualityPolymer Synthesis Expert
- 2026.09.12How German Implant Makers Select Medical Polymers for Long-Term BiocompatibilityPolymer Synthesis Expert
The VitalSync Intelligence Brief
Receive daily deep-dives into MedTech innovations and regulatory shifts.